


Last updated: August 2026
by Jess Knauf, Co-Founder, Family Law Service. Reviewed by Belinda Atkins, Managing Director, Family Legal Ltd. Information is current as of 10 August 2026.
Quick Summary
- Both people in a divorce have a legal duty to give full and frank financial disclosure, and that duty does not end when the paperwork is signed.
- Common hiding places include undeclared bonuses, company accounts, crypto holdings, cash transfers to family and deliberately deferred income.
- The court can draw adverse inferences, order costs against someone who conceals assets, and set aside a financial order that was built on a lie.
- Whether you make a joint divorce application or a sole divorce application does not change the disclosure duty, though it can affect timing and control.
- Do not go looking through your ex’s documents or devices without permission. It can damage your case and cost you money.
- A financial order made by consent is what actually protects your savings for the long term.
Hidden assets divorce UK
Hidden assets in a UK divorce are any money, property, pensions, business interests or investments that one person fails to declare during financial disclosure. Non-disclosure is a breach of a legal duty owed to the court, not just to your ex. If assets come to light later, the court has the power to reopen a settlement and redistribute what was hidden.
If you have found yourself typing hidden assets divorce UK into a search bar at eleven at night, you are in good company. It usually starts small. A bonus that was mentioned once and never again. A business that suddenly has a terrible year. A savings account that emptied itself the month you both agreed to separate. None of it proves anything on its own, but together it leaves you wondering whether the numbers in front of you are the real numbers.
That worry matters, because your settlement is only as fair as the information it was based on. Before you do anything else, it helps to understand how everything gets divided, because the rules on disclosure sit underneath all of it. This guide explains what counts as a hidden asset, the warning signs worth taking seriously, what the court can do about it, and the practical steps that protect your savings while you find out.
Hidden Assets Divorce UK: What the Law Actually Requires
In England and Wales, anyone dealing with finances on divorce has a duty of full and frank disclosure. That means declaring everything you own, everything you owe and everything you earn, whether or not you think your ex knows about it, and whether or not you believe it should be shared.
Disclosure is usually done through Form E, the court’s financial statement. It runs to around 27 pages and asks for property, bank accounts, investments, pensions, business interests, income, debts and any assets transferred in the last twelve months. It is signed with a statement of truth. Signing it knowing it is incomplete is not a technicality. It is a false statement to the court.
The court’s power to divide finances comes from section 25 of the Matrimonial Causes Act 1973, which requires a judge to look at all the circumstances of the case. A judge cannot weigh what a judge cannot see, which is exactly why the duty is drawn so widely.
The duty does not expire
Disclosure is a continuing duty. If your circumstances change materially between filling in Form E and the order being approved, for example a business sale completing or a redundancy package landing, that has to be disclosed too. In Sharland v Sharland [2015] UKSC 60 the Supreme Court set aside a settlement where a husband had misled his wife about the value of his company, and made clear that fraud unravels a consent order in much the same way it unravels any other agreement. The decision in Gohil v Gohil [2015] UKSC 61 was handed down on the same day and took a similar line on deliberate non-disclosure.
“In the cases we see, deliberate large-scale concealment is rarer than people fear. What is far more common is partial disclosure: the pension that gets forgotten, the director’s loan account nobody mentions, the bonus that is ‘not guaranteed’. Our advice is always the same. Do not accuse, ask. A specific written question about a specific figure gets you further than a general suspicion ever will, and it builds a paper trail if you do end up in front of a judge.”
Jess Knauf, Co-Founder, Family Law Service
Where Assets Are Most Often Hidden
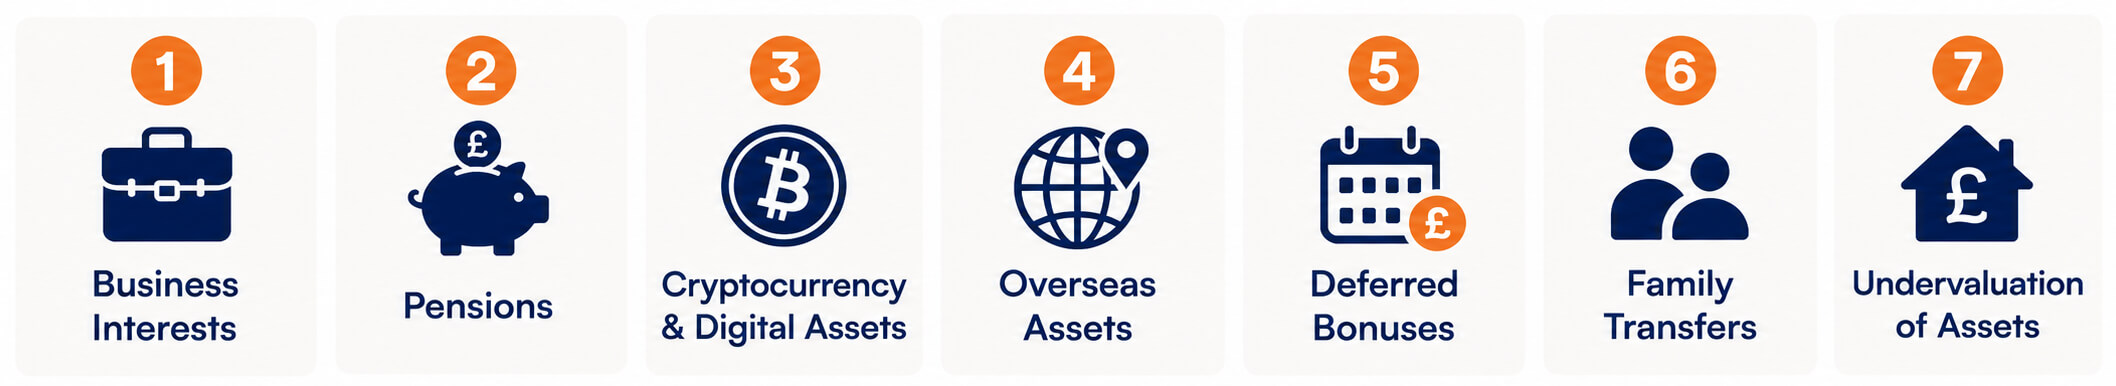
Money rarely disappears into a suitcase under a bed. It gets parked somewhere that looks legitimate. The most common places are:
- Company accounts: profit left inside a limited company, a director’s loan account, or expenses run through the business that are really personal spending
- Deferred income: a bonus, commission or share option delayed until after the financial order is sealed
- Pensions: often the second largest asset after the family home, and the one most frequently understated or ignored entirely
- Cryptocurrency: holdings on exchanges or in private wallets, which people wrongly assume are untraceable
- Transfers to family and friends: cash moved to a parent or sibling and described as repaying an old loan
- Overseas accounts and property: assets held in another jurisdiction, sometimes in a relative’s name
- Undervalued assets: a business, a property or a share portfolio presented at a convenient valuation rather than a realistic one
Warning signs worth taking seriously
Any one of these can have an innocent explanation. Several together are worth asking about in writing: a sudden drop in reported income that does not match your lifestyle, statements produced with pages missing, refusal to give bank statements for accounts you know exist, new accounts opened shortly before separation, unusually large or round transfers, business paperwork you were previously copied into and now are not, and a strong push to settle quickly and quietly before anyone has to fill in a form.
Case study: the bonus that was “not guaranteed”
A client came to us convinced her husband was understating his earnings. His Form E showed salary only, with a note that bonuses were discretionary. Rather than accusing him, we helped her put four short written questions to him: the bonus paid in each of the last three years, the scheme rules, the payment date, and whether any award had been deferred. The answers showed a pattern of substantial annual bonuses, one of which was due to be paid ten weeks later. It was brought into the settlement without a contested hearing.
Not Sure Whether the Figures Add Up?
A one hour fixed-fee session with a family law specialist will tell you whether your concerns are worth pursuing and what to ask for next. Far quicker and far less expensive than instructing a solicitor on an hourly rate to work it out for you.
Does a Joint Divorce Application or a Sole Divorce Application Change Anything?
Since no-fault divorce came in, you can apply either way. A joint divorce application is made by both of you together as applicant one and applicant two. A sole divorce application is made by one person, with the other named as the respondent. The court fee is the same either way, currently £628 as of July 2026 (see the Ministry of Justice fees announcement), and you can apply online through GOV.UK.
Neither route changes the duty of disclosure. It applies identically to both. What does differ is control. In a joint divorce application both people have to move together at each stage, so if one of you stalls, the other cannot simply push on. A sole divorce application lets you control the pace, which matters if you suspect someone is running down the clock while assets move around.
The point people most often miss is that the divorce itself does not touch the money at all. Ending the marriage and dividing the finances are two separate processes. Your financial claims stay open until a court makes a financial order, which is why a clean break consent order matters so much, and why filing for divorce alone protects nothing.
How to Protect Your Savings While You Find Out
There is a practical difference between protecting what you have and hiding it. The first is sensible. The second is the behaviour this article is about. Our fuller guide on how to protect savings during a divorce goes into more detail, and these are the steps that matter most when hidden assets are a concern.
Step 1: Build your own picture first
Gather what you can lawfully access: joint account statements, your own payslips and pension statements, mortgage paperwork, tax returns you filed jointly, and anything already sent to you. Note down what you remember about accounts, policies and business interests, with rough dates. Memory fades quickly once proceedings start.
Step 2: Secure joint funds sensibly
If you genuinely fear a joint account will be emptied, you can ask the bank to change it so both signatures are needed. Register a home rights notice with the Land Registry if the family home is in your ex’s sole name, which stops it being sold or remortgaged without your knowledge. Do not empty accounts yourself. Anything you take out will be added back into the pot and it will not look good.
Step 3: Ask specific, written questions
Once Form E has been exchanged, each side can send a schedule of deficiencies, which is a written list of questions about anything missing or unclear. Precise questions are far more effective than broad ones. “Please provide the statements for account ending 4471 for the twelve months to March” is answerable. “Tell me about your money” is not. If you would like someone to review the disclosure and draft those questions, our case review service does exactly that for a fixed fee.
Step 4: Use the court’s powers if you have to
If questions go unanswered, an application to court on Form A opens the financial remedy process, with a timetable the court enforces. The fee for a contested financial order is £321 as of July 2026. The court can order disclosure from third parties such as banks and employers, and in serious cases can freeze assets under section 37 of the Matrimonial Causes Act 1973 to stop a disposal designed to defeat your claim.
Hidden Assets Divorce UK: The Top 10 Mistakes People Make
Some of these come up again and again, and several of them cost people more than the assets they were worried about in the first place. They sit alongside the wider mistakes people make in financial divorce settlements.
- Self-help snooping. Reading your ex’s emails, photographing documents from a locked drawer or logging into their accounts. Following Imerman v Tchenguiz, material obtained this way usually has to be handed back unread, and you can face a costs order or worse.
- Making an accusation you cannot evidence. It hardens the other side, raises legal costs and can undermine your credibility on the points you can prove.
- Accepting a summary instead of source documents. A typed schedule is not a bank statement. Ask for the underlying paperwork.
- Forgetting pensions. A cash equivalent value can look small next to a house and still be worth far more over a lifetime.
- Taking a business valuation on trust. Owner-provided figures are a starting point, not an answer.
- Settling quickly to end the conflict. Pressure to sign “before the lawyers get involved” is itself a warning sign.
- Spending more on investigation than the asset is worth. Forensic accountancy is expensive. Ask what the realistic recovery is first.
- Relying on a verbal promise. Only a sealed court order is enforceable.
- Signing an order without a full asset schedule. If it is not listed, it is very hard to argue about later.
- Leaving financial claims open. Without a clean break order, either of you can make a claim years afterwards, including against money you earn after the divorce.
What Happens If Hidden Assets Are Found
Courts take non-disclosure seriously, and the consequences are real. A judge can draw adverse inferences, meaning they assume the undisclosed asset exists and is worth more rather than less. They can add back money that was deliberately dissipated and treat it as though it were still there. They can order the person who concealed it to pay the other side’s costs, which in a contested case can run well into five figures.
Most importantly, an order can be set aside. If a settlement was reached on the back of dishonest disclosure, the injured party can apply to reopen it and have the finances decided again on the true figures. Deliberately misleading the court in a signed statement of truth can also amount to contempt of court.
Mediate UK
Want Full Disclosure Without a Court Fight?
Family Law Service does not offer mediation, but our sister company Mediate UK does. Financial mediation runs on open disclosure between you both, and it is usually quicker and considerably less expensive than a contested financial remedy application.
Locking In Your Settlement Once You Have the Full Picture
Once you are satisfied the disclosure is complete, the agreement needs turning into a sealed consent order. Until a judge approves it, nothing is binding and nothing is protected. The court fee for a financial order by consent is £62 as of July 2026, and our fixed-fee drafting service is £499, which is a fraction of what the same document usually costs through a high street firm.
If you would like a view on whether what is being offered is reasonable before you commit, our AI Barrister Review gives you a written assessment of your financial position based on the same principles a court would apply.
Summary
Concerns about hidden assets in a UK divorce are common, and the law is firmly on the side of the person asking honest questions. Full and frank disclosure is a duty owed to the court, it continues until the order is sealed, and the court has real powers to enforce it: adverse inferences, costs orders, third party disclosure, freezing orders and setting aside a settlement obtained by deception.
The practical route is unglamorous but effective. Gather what you can lawfully access, protect joint funds properly rather than defensively, ask precise written questions, and escalate to court only if the answers do not come. Whether you go down the joint divorce application or sole divorce application route, remember that the divorce itself settles nothing financially. Only a sealed financial order does that.
Frequently Asked Questions
How do I prove my ex is hiding assets in a UK divorce?
Start with the disclosure process itself. Compare the Form E against the lifestyle and documents you already have, then send written questions about specific gaps. If the answers are inadequate, the court can order disclosure directly from banks, employers, accountants and pension providers. You do not need to prove concealment yourself before the court will act.
Can a financial order be overturned if assets were hidden?
Yes. If a consent order was based on materially false or incomplete disclosure, you can apply to set it aside and have the finances decided again on the correct figures. Apply as soon as you find out, because delay can weaken your position.
Is it illegal to look at my ex’s bank statements?
Taking, copying or accessing your ex’s confidential documents without permission can breach confidentiality and data protection law, and may amount to a criminal offence if you access their devices or accounts. Documents obtained that way normally have to be returned unread, and you risk a costs order. Ask for them through disclosure instead.
Can cryptocurrency be hidden in a divorce?
Crypto must be disclosed like any other asset. It is less anonymous than people assume, because purchases usually leave a trail through a bank account and UK exchanges are subject to disclosure orders. Unexplained transfers to an exchange are a reasonable thing to ask about.
Does a joint divorce application mean we have to share financial information?
The disclosure duty is the same whether you make a joint divorce application or a sole divorce application. The divorce application deals only with ending the marriage. Finances are a separate process with their own disclosure requirements.
How much does it cost to investigate hidden assets?
It varies widely. Written questions through the standard disclosure process cost very little. A forensic accountant instructed to value a business or trace funds can cost several thousand pounds. Get advice on the likely recovery before committing to the more expensive route.
You Might Also Find Helpful
Worried the Figures Are Not the Full Picture?
We have helped more than 23,000 people sort out the legal side of separation, with 715+ 5-star reviews. Every service is fixed fee, so you know exactly what you are paying before you start, including our clean break consent order at £499.